Rahn: The Law of Pledge in Imam al-Nawawi’s Minhaj al-Talibin
Part 2: Transactions (Mu’amalat) – Pledge (Rahn)
Part of a series on the structure of Minhaj al-Talibin, the classical Shafi’i legal manual. Section 2 of Part 2 (Transactions).
Introduction
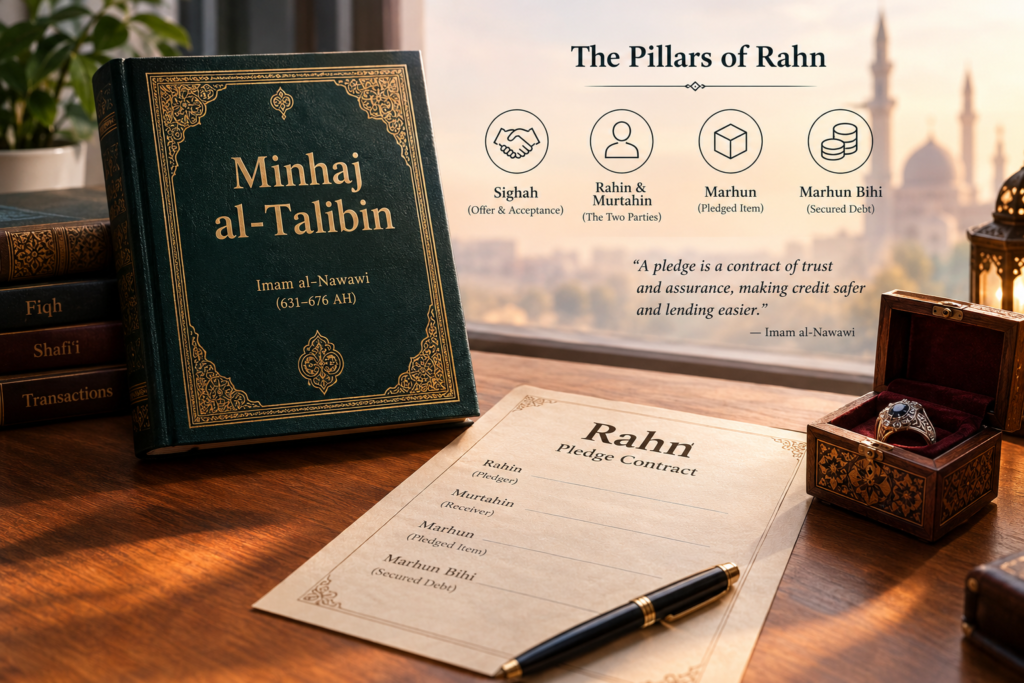
After the Book of Sales, Imam al-Nawawi (631–676 AH / 1233–1277 CE) turns to the Book of Pledge (Kitab al-Rahn). Where sale transfers ownership, a pledge does something different: it places an item as security for a debt, so that the creditor can be repaid from it if the debtor fails to pay. It is a contract of trust and assurance, and it makes credit safer, which in turn makes lending easier.
The legal basis is found in the Qur’an, in the verse on written debt (al-Baqarah 2:283), which mentions pledges taken in the absence of a scribe during travel. It is also supported by the report that the Prophet pledged his armor to a merchant in return for grain. This article follows the main themes of the book in the general order of the Minhaj.
1. The meaning and the pillars of pledge
In legal terms, a pledge means making a tangible item security for a debt, to be paid from its value if the debt cannot be settled. The parties are the one who gives the pledge (rahin) and the one who receives it (murtahin). The school identifies the essential elements as:
- The wording (sighah): an offer and acceptance, as in other contracts.
- The two parties: each must be competent to dispose of property.
- The pledged item (marhun).
- The secured debt (marhun bihi).
Al-Nawawi notes that a pledge is valid when it is made in connection with a debt, whether the debt arises from a sale, a loan, or another cause, and whether the parties are at home or traveling.
2. Conditions of the pledged item
The item pledged must be something that can be sold to repay the debt. As a result:
- It must be a pure item that can lawfully be owned and traded.
- It must be capable of delivery, and the owner must have the right to dispose of it.
- It must be specific and known.
- In the school’s position, it must be a tangible item rather than a debt owed by a third party.
This condition follows from the purpose of the contract. If the item could not be sold, the creditor would have no real security.
3. Conditions of the secured debt
The debt must be established and binding. The school’s position is that a pledge made before the debt exists is not valid, since there is nothing yet to secure. Al-Nawawi also addresses debts that are not yet binding, such as a price payable under a condition, and gives the school’s rulings on these.
4. Possession and the binding of the contract
A central feature of the book is the role of possession (qabd). Following the verse that speaks of pledges “taken in hand,” the school holds that the pledge becomes binding only once the creditor, or a trusted third party agreed by both sides, has taken possession of the item. Before that, the debtor may withdraw. After possession, the debtor can no longer cancel the pledge on their own.
The book also discusses what counts as possession for different types of property, and what happens to the contract if the debtor dies, becomes incompetent, or sells the item before it is handed over.
5. Stipulations within the contract
The parties may add conditions to a pledge, and al-Nawawi lists which are valid and which are not. Conditions consistent with the purpose of the contract are acceptable, such as agreeing on a trustee to hold the item. Conditions that undermine its purpose or harm one party are void, such as a stipulation that the creditor will keep the item if the debt is not paid by a certain date. This was a custom of the pre-Islamic period, and the tradition forbids it. In the school, the pledge is never forfeited, and the creditor is only entitled to the value needed to settle the debt.
6. Dealing with the pledged item
The book clarifies what each party may do while the pledge is in place:
- The debtor remains the owner but may not dispose of the item in a way that harms the creditor’s security, such as selling it, giving it away, or renting it out, without the creditor’s permission. Actions that do not harm the security, such as freeing the item from a defect, are treated separately.
- The creditor holds the item as a trust (amanah). He is not responsible for loss unless he was negligent or misused it, and he may not use it without the owner’s permission.
The school also discusses who may keep the pledge, the case of a trustee, and the effect of damage or loss, which generally falls on the debtor’s account, since the debt remains.
7. Benefits, growth, and expenses
Al-Nawawi explains that the pledged item remains the property of the debtor, so its profits and increases, such as milk, offspring, or fruit, belong to the debtor, though in the school’s position they do not become part of the security unless they were included. The expenses of maintaining the item, such as feeding an animal, fall on the owner. This applies the general principle that benefit and cost go together.
8. Sale of the pledge and repayment
When the debt falls due and is not paid, the creditor may request that the pledged item be sold to recover the amount owed. The school describes the process: the debtor is asked to sell it or give permission, and if he refuses, the judge may order the sale. The proceeds are used to repay the debt, and any surplus goes back to the debtor. If the proceeds fall short, the debtor remains liable for the balance. The book also describes how the order of claims works if the debtor has several creditors.
9. Disputes and ending the pledge
The book discusses the common disputes that arise, such as disagreement over the amount of the debt, the value of the pledged item, or whether the item has been returned. For each, it states who bears the burden of proof and who is believed under oath. The pledge ends when the debt is repaid or waived, when the creditor releases the item, or when the item is destroyed, with the distinctions the school draws between these cases.
Why the order matters
The book follows the life of the contract from beginning to end. It starts with the definition and the elements, then the conditions of the item and debt, then possession, which is the moment of binding. Next it describes the rights and duties of each party during the pledge, and ends with enforcement, disputes, and termination. This order reflects how a real pledge unfolds: formation, holding, and resolution.
Closing reflection
For al-Nawawi, the pledge reflects a balance that appears throughout the law of transactions. The creditor is entitled to security for what he has lent, but the debtor remains the owner, and may not be stripped of his property beyond what the debt requires. The prohibition of forfeiture captures this balance, protecting trust in credit while guarding against exploitation.
Note: This article summarizes the general Shafi’i position as presented in Minhaj al-Talibin. Details can vary between editions and commentaries, and modern secured-lending arrangements involve additional considerations. Readers who need a precise ruling should consult a qualified teacher or scholar.